

Buying your first home?
Let’s make it make sense. 🏡
Buying your first home is exciting — but suddenly everyone starts throwing around words like borrowing capacity, LMI, pre-approval, deposits, grants and government schemes and somehow you're expected to know what all of it means.
You don't.
And you don't need to figure it out before you talk to us.
At Lending Solved, we'll help you understand where you're at now, what buying could realistically look like for you and what your next steps could be.
Whether you're hoping to buy now, in six months or sometime next year, we'd much rather talk to you early and help you make a plan.


First Home Buyer questions we get ALL. THE. TIME.
-
We’re all unique when it comes to our finances and borrowing needs. Contact us today, we can help with calculations based on your circumstances
-
Our guides to loan types and features will help you learn about the main options available. There are hundreds of different home loans available, so talk to us today.
-
Usually between 5% - 10% of the value of a property. Speak with us to discuss your options for a deposit.
-
Go to our Repayment Calculator for an estimate. Because there are so many different loan products, some with lower introductory rates, talk to us today about the deals currently available, and we’ll work with you to find a loan setup that’s right for you.
-
Most lenders offer flexible repayment options to suit your pay cycle. If you aim to make weekly or fortnightly repayments, instead of monthly, you will make more payments in a year, which can potentially shave dollars and time off your loan.
-
This is a grant available to Australian citizens or permanent residents who wish to buy or build their first home, which will be their principal place of residence within 12 months of settlement. Contact us directly to find out more about eligibility requirements in your state and how much grant money you could receive.
-
There are a number of fees and costs involved when buying a property. To help avoid any surprises, the list below sets out many of the usual costs:
Stamp duty — This is the big one. All other costs are relatively small by comparison. Stamp duty rates vary between state and territory governments and also depend on the value of the property you buy. You may also have to pay stamp duty on the mortgage itself. To estimate your possible stamp duty charge, visit our Stamp Duty Calculator.
Legal/conveyancing fees — Generally around $1,000 – $1500, these fees cover all the legal requirements around your property purchase, including title searches.
Building inspection — This should be carried out by a qualified expert, such as a structural engineer before you purchase the property. Your Contract of Sale should be subject to the building inspection, so if there are any structural problems you have the option to withdraw from the purchase without any significant financial penalties. A building inspection and report can cost up to $1,000, depending on the size of the property. Your conveyancer will usually arrange this inspection, and you will usually pay for it as part of their total invoice at settlement (in addition to the conveyancing fees).
Pest inspection — Also to be carried out before purchase to ensure the property is free of problems, such as white ants. Your Contract of Sale should be subject to the pest inspection, so if any unwanted crawlies are found you may have the option to withdraw from the purchase without any significant financial penalties. Allow up to $500 depending on the size of the property. Your real estate agent or conveyancer may arrange this inspection, and you will usually pay for it as part of their total invoice at settlement (in addition to the conveyancing fees).
Lender costs — Most lenders charge establishment fees to help cover the costs of their own valuation as well as administration fees. We will let you know what your lender charges but allow about $600 to $800.
Moving costs — Don’t forget to factor in the cost of a removalist if you plan on using one.
Mortgage Insurance costs — If you borrow more than 80% of the purchase price of the property, you’ll also need to pay Lender Mortgage Insurance. You may also consider whether to take out Mortgage Protection Insurance.
Ongoing costs — If you buy a strata title, regular strata fees are payable. You will need to include council and water rates along with regular loan repayments. It is important to also consider building insurance and contents insurance. Your lender will probably require a minimum sum insured for the building to cover the loan.
NOT READY TO TALK TO US YET? Start here. It’s free. 🏡
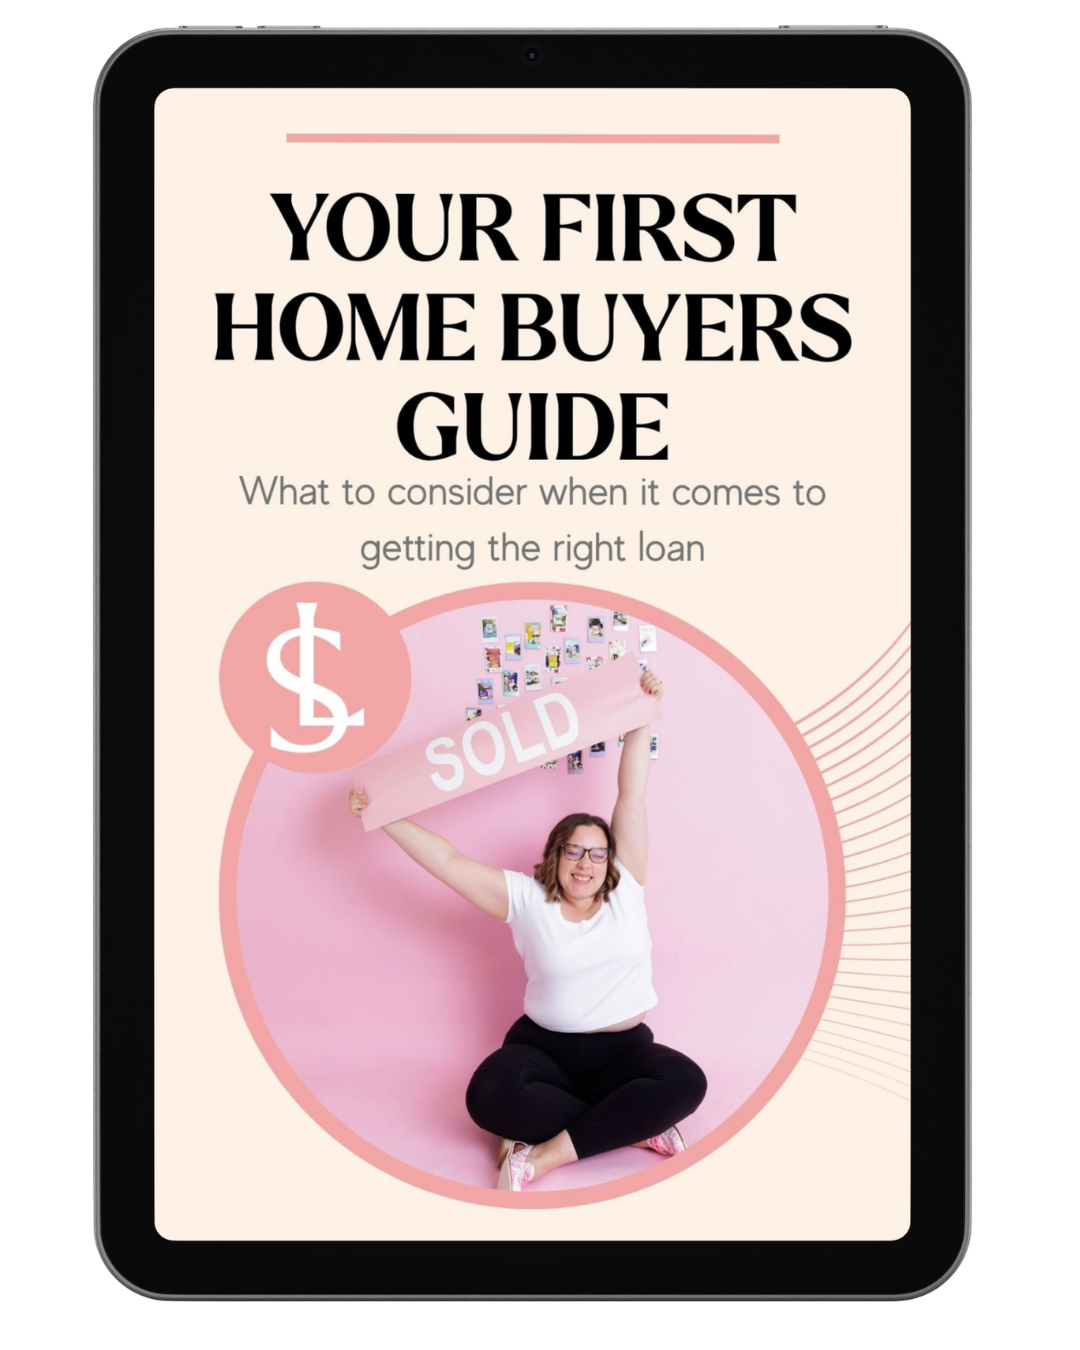
Get my FREE First Home Buyer Guide
We've put together our First Home Buyer Guide for that “I want to buy a house, but I don't really know where to start” stage.
Inside, we'll walk you through things like:
✓ Saving for your deposit
✓ LMI and how it works
✓ Working out what you can afford
✓ Different home loan types
✓ Family assistance
✓ Rentvesting
✓ First home buyer schemes and incentives
✓ What to do next
And the Guide is just the start…
You'll also get access to our:
🎥 First Home Buyer Masterclass
Watch our webinar on demand and let us talk you through the process.
✏️ First Home Buyer Workbook
Work alongside the Masterclass and start putting your own plans, numbers and questions together.
“I had such a great experience with Jess and her team at Lending Solved. From start to finish, nothing was ever too much trouble and no question was ever a “dumb” question — everything was explained clearly and patiently. The whole process felt easy and stress-free thanks to their support and knowledge. I couldn’t recommend them more highly!”
Alice - NSW
1. WE START WITH YOU
We start with a chat about where you're at, what you're hoping to achieve and when you'd ideally like to buy.
You don't need to be “ready”. That's what we're figuring out.
SO, WHAT HAPPENS WHEN YOU WORK WITH US?
No bank jargon. No guessing what happens next. No being left to figure it out yourself.
2. WE LOOK AT THE NUMBERS
We'll look at your income, expenses, deposit and commitments and start putting some real numbers around what buying could look like for you.
3. WE MAKE A PLAN
Ready to go? Amazing.
Not quite there yet? That's okay too. We'll explain what might need to happen first and give you something actually useful to work towards.
4. WHEN IT'S TIME, WE DO THE HARD STUFF
When you're ready to move forward, we'll help with lender selection, your application, approval and the finance process through to settlement.